UK First-Time Buyer Schemes: A Comprehensive Comparison
Embarking on the journey to buy your first home in the UK can feel daunting, but thankfully, the government offers several initiatives to help make this dream a reality. Understanding the various UK first-time buyer schemes is crucial for anyone looking to step onto the property ladder. These schemes are designed to provide financial assistance, making homeownership more accessible, especially for those struggling to save a substantial deposit.
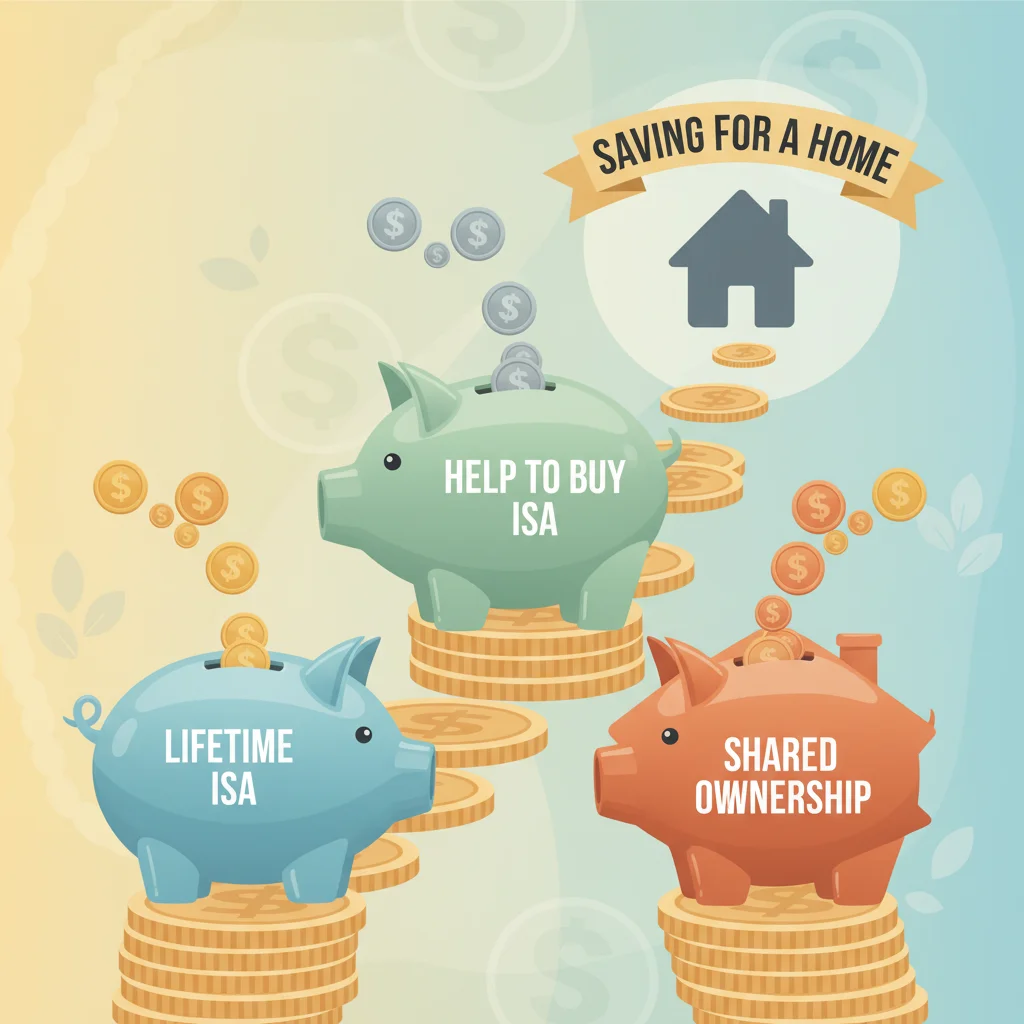
Choosing the right scheme can significantly impact your savings strategy and the type of home you can afford. We’ll delve into the specifics of the Lifetime ISA, the Help to Buy ISA, and Shared Ownership, offering a clear comparison to help you make an informed decision. Each scheme has its unique advantages, eligibility criteria, and limitations, so a thorough understanding is key.
Lifetime ISA (LISA): A Flexible Savings Option
The Lifetime ISA, often simply called LISA, is a popular choice among first-time buyers due to its generous government bonus. It’s a savings and investment product designed to help individuals aged 18 to 39 save for their first home or for retirement. You can save up to £4,000 each tax year, and the government will add a 25% bonus to your contributions. This means if you save the maximum £4,000, you’ll receive an extra £1,000 from the government, boosting your savings significantly.
The LISA can be opened by anyone aged 18 to 39, and you can continue contributing until you turn 50. The bonus is paid monthly, which means your savings grow faster with compound interest. However, there are rules around withdrawals. If you withdraw money for anything other than buying your first home (up to £450,000) or for retirement after age 60, you’ll face a 25% withdrawal charge. This charge means you could end up with less than you originally put in, so it’s important to be committed to your homebuying goal when opening a LISA.
Key Features of the Lifetime ISA:
- Government Bonus: 25% on contributions, up to £1,000 per year.
- Contribution Limit: £4,000 per tax year.
- Age Eligibility: Open between 18 and 39, contribute until 50.
- Property Value Limit: Property must be £450,000 or less.
- Withdrawal Penalties: 25% charge for non-qualifying withdrawals.
The flexibility of investing your LISA funds in stocks and shares or keeping them in cash also provides different growth potentials, depending on your risk tolerance. It’s a powerful tool for those with a clear plan to buy their first home within a reasonable timeframe, offering a substantial boost to their deposit.
Help to Buy ISA: The Predecessor Scheme
While no longer open to new applicants since November 2019, the Help to Buy ISA remains a vital scheme for many first-time buyers who opened one before the deadline. If you have a Help to Buy ISA, you can continue to save into it until November 2029, and you must claim your bonus by November 2030. Similar to the LISA, it offers a 25% government bonus on your savings, but with different contribution limits and overall caps. You could save up to £200 per month, with an initial deposit of up to £1,200 in the first month.
The maximum government bonus you can receive from a Help to Buy ISA is £3,000, which requires you to have saved £12,000. The bonus is paid when you are ready to complete your home purchase and is sent directly to your solicitor. Unlike the LISA, there are no penalties for withdrawing money for purposes other than buying a home; you simply won’t receive the government bonus on those funds. This makes it a slightly less restrictive option for those who might need to access their savings for other emergencies, though it doesn’t offer the same long-term growth potential as the LISA for homebuying.
The property value limit for homes purchased with a Help to Buy ISA is £250,000 outside London and £450,000 in London. This limit is lower than the LISA for properties outside the capital, which could be a significant factor depending on where you plan to buy. It’s crucial for those with an existing Help to Buy ISA to understand these differences, especially if they are also considering a LISA or have both.
Shared Ownership: A Stepping Stone to Full Ownership
Shared Ownership is a different kind of UK first-time buyer scheme, focusing on making homeownership affordable by allowing you to buy a share of a property and pay rent on the remaining portion. This scheme is ideal for those who can’t afford to buy a home outright on the open market, even with the help of a deposit scheme. You typically buy between 25% and 75% of a home’s value from a housing association, and then pay rent on the share you don’t own. The deposit required is usually much lower than buying a home outright, as it’s based on the share you purchase.
One of the significant advantages of Shared Ownership is the ability to ‘staircase’ – meaning you can buy more shares in your home over time, eventually owning 100% of it if you wish. This flexibility allows you to increase your equity as your financial situation improves. However, there are also considerations, such as paying rent to the housing association, service charges, and ground rent, in addition to your mortgage repayments. These combined costs can sometimes be similar to, or even higher than, a full mortgage payment on a smaller property.
Eligibility for Shared Ownership usually requires your household income to be less than £80,000 a year outside London, or £90,000 a year in London. You must also be a first-time buyer, or a former homeowner who can’t afford to buy a home outright. The properties available through Shared Ownership are typically newly built homes or existing properties being resold by housing associations. It’s a great option for those who want to get on the property ladder sooner, even if it means not owning the entire property from day one.
Comparing the Schemes: Which One is Right for You?
Deciding between the Lifetime ISA, Help to Buy ISA, and Shared Ownership depends heavily on your personal circumstances, savings goals, and timeline. The Lifetime ISA offers the highest potential government bonus over time, especially if you start saving early and maximise your contributions. Its higher property value limit of £450,000 across the UK also makes it suitable for a wider range of properties. However, the strict withdrawal penalties for non-homebuying purposes make it less flexible if your plans change.
For those who opened a Help to Buy ISA before the deadline, it still represents a valuable saving tool. Its main advantage is the lack of withdrawal penalties, offering more financial freedom if you need to access your funds for other reasons. However, the lower monthly contribution limit and the maximum bonus cap mean it might not grow as quickly as a LISA. The property value limits are also a key consideration, particularly if you’re looking at homes outside of London.
Shared Ownership, on the other hand, isn’t a savings scheme but a direct route to homeownership for those with smaller deposits and lower incomes. It allows you to become a homeowner with a smaller initial outlay, but introduces the complexities of paying rent alongside your mortgage, plus service charges. While staircasing offers a path to full ownership, it can be a lengthy process with additional fees involved. It’s a great solution for immediate housing needs when outright purchase isn’t feasible, but requires careful budgeting for ongoing costs.
Navigating Eligibility and Maximising Benefits
Understanding the specific eligibility criteria for each of these UK first-time buyer schemes is paramount. For both the Lifetime ISA and Help to Buy ISA, you must be a first-time buyer, meaning you’ve never owned any interest in a residential property, either in the UK or abroad. For the LISA, you must be aged between 18 and 39 to open the account, though you can contribute until you’re 50. The Help to Buy ISA, as mentioned, is closed to new applicants, but existing account holders can continue to benefit.
To maximise the benefits of a LISA, starting early and contributing consistently is key to taking full advantage of the annual £1,000 bonus. If you have an existing Help to Buy ISA, consider whether it’s more beneficial to continue with it or transfer funds to a LISA, if eligible, to potentially gain a higher overall bonus and benefit from the higher property value limit. Remember that you can’t use both a Help to Buy ISA and a LISA bonus on the same property purchase, so careful planning is essential.
For Shared Ownership, the income thresholds are crucial, as is your status as a first-time buyer or a former homeowner who can no longer afford to buy. It’s also important to consider the location and type of properties available through Shared Ownership schemes in your desired area. Researching local housing associations and their current listings can provide a clear picture of what’s available. Always seek independent financial advice to understand the long-term financial implications of each scheme before committing.
Frequently Asked Questions
Can I have both a Lifetime ISA and a Help to Buy ISA?
Yes, you can hold both a Lifetime ISA and a Help to Buy ISA simultaneously. However, you can only use the government bonus from one of these schemes towards the purchase of your first home. You must choose which bonus to use when you complete your property purchase.
What happens if I withdraw money from my LISA for a non-qualifying reason?
If you withdraw money from your Lifetime ISA for any reason other than buying your first home (up to £450,000) or after you turn 60, you will incur a 25% government withdrawal charge. This charge means you could end up with less than you originally contributed.
Is Shared Ownership only for new build properties?
While many Shared Ownership properties are new builds, it’s also possible to purchase existing properties through the scheme. These are typically homes being resold by current Shared Ownership tenants through their housing association. Availability varies by region and housing association.
How long does it take to get the bonus from a Help to Buy ISA?
The Help to Buy ISA bonus is applied for by your solicitor when you are close to completing your home purchase. It can take up to 10 working days for the bonus funds to be released and transferred to your solicitor, so it’s important to factor this into your timeline.
Can I use Shared Ownership if I’ve owned a home before?
Yes, you can use Shared Ownership even if you’ve owned a home before, provided you can demonstrate that you’re unable to afford to buy a property suitable for your needs on the open market now. This is a key difference from the LISA and Help to Buy ISA, which are strictly for first-time buyers.
Official Resources
- GOV.UK – Lifetime ISA
- GOV.UK – Help to Buy ISA
- GOV.UK – Shared Ownership scheme
- MoneyHelper – Government schemes to help you buy a home
Conclusion
Navigating the landscape of UK first-time buyer schemes can seem complex, but understanding the nuances of each option is your first step towards successful homeownership. Whether you’re drawn to the significant government boost offered by the Lifetime ISA, leveraging an existing Help to Buy ISA, or considering Shared Ownership as a practical route to get on the property ladder, each scheme presents unique opportunities and considerations. Your choice should align with your financial situation, saving capacity, desired property type, and long-term goals.
Remember that careful planning, understanding eligibility criteria, and being aware of potential limitations are crucial. Don’t hesitate to seek independent financial advice to discuss your personal circumstances and determine the most suitable path for you. With the right strategy, these government-backed schemes can significantly ease the financial burden of purchasing your first home, transforming your dream of homeownership into a tangible reality. Start exploring these options today to unlock the door to your future home.