UK Buy-to-Let Surcharge: Navigating the 3% Stamp Duty
The UK buy-to-let surcharge of 3% Stamp Duty Land Tax significantly impacts property investors. This guide provides essential information on understanding the surcharge, calculating costs, exploring exemptions, and navigating the complexities of the UK property market for landlords.
By: Michael Sete on August 22, 2026
Última atualização em: agosto 24, 2026
The landscape of property investment in the UK has seen significant changes over recent years, particularly for those looking to expand their portfolio with additional properties. One of the most impactful adjustments for landlords and investors is the introduction of the 3% Stamp Duty Land Tax (SDLT) surcharge, commonly known as the UK buy-to-let surcharge. This additional tax has reshaped how many approach property acquisition, making careful financial planning more crucial than ever.
Understanding this surcharge is not just about knowing an extra cost; it’s about comprehending its nuances, potential exemptions, and how it integrates into the broader context of property investment. Whether you’re a seasoned landlord or just starting your journey in the buy-to-let market, grasping the intricacies of this tax is fundamental to making informed decisions and ensuring the profitability of your ventures. This article aims to demystify the 3% Stamp Duty surcharge, providing a comprehensive guide to help you navigate its complexities.
What is the 3% Stamp Duty Surcharge?
The 3% Stamp Duty surcharge, officially known as the higher rates of SDLT for additional dwellings, was introduced by the UK government to cool down the buy-to-let market and to help first-time buyers compete more effectively. It applies to the purchase of residential properties where, at the end of the day of the transaction, the buyer will own two or more residential properties. This means if you already own a home, and you’re buying another one—whether it’s a rental property, a holiday home, or even a second home for personal use—you’ll likely be subject to this additional 3% on top of the standard Stamp Duty rates.
It’s important to understand that this surcharge isn’t a flat fee; it’s an additional percentage applied to each Stamp Duty band. For example, if the standard rate for a portion of the property’s value is 2%, with the surcharge, it becomes 5%. This significantly increases the upfront cost of purchasing an additional property. The government’s intention behind this measure was to create a more level playing field in the housing market, but its impact on investors has been substantial, requiring a recalculation of investment viability for many.
The surcharge aims to deter individuals from accumulating multiple properties, thereby theoretically freeing up more homes for owner-occupiers. While the policy’s effectiveness in achieving this goal is a subject of ongoing debate among economists and property experts, its direct financial implications for investors are undeniable. Therefore, any prospective or current property investor must factor this additional cost into their financial models and projections when considering new acquisitions. Failing to account for the UK buy-to-let surcharge can lead to unexpected expenses that significantly erode potential returns.
Who is Affected by the UK Buy-to-Let Surcharge?
The UK buy-to-let surcharge primarily affects individuals or entities purchasing an additional residential property when they already own one or more. This includes a broad spectrum of buyers. For instance, if you own your main residence and decide to buy a second property to rent out, you will almost certainly pay the surcharge. The same applies if you are buying a holiday home, even if it’s not intended for rental income. The key criterion is owning more than one residential property at the end of the transaction day.
Companies and trusts purchasing residential properties are also generally subject to the higher rates, regardless of whether they own other properties, with some specific exceptions. This particular aspect ensures that investors cannot simply use corporate structures to circumvent the additional tax burden. The rules are designed to be comprehensive, aiming to capture most scenarios where an additional residential property is acquired, thereby reinforcing the government’s policy objectives.
However, there are specific situations where the surcharge might not apply, even if you own multiple properties. For example, if you are replacing your main residence, and there is a temporary overlap in ownership, you might be eligible for a refund of the higher rates, provided you sell your old main residence within a certain timeframe. Understanding these specific scenarios and the exact definitions of ‘main residence’ and ‘additional property’ is crucial for accurate assessment of your tax liability. It’s not always as straightforward as it seems, and each case can have unique elements that influence the final Stamp Duty calculation.
Calculating Your Stamp Duty Liability
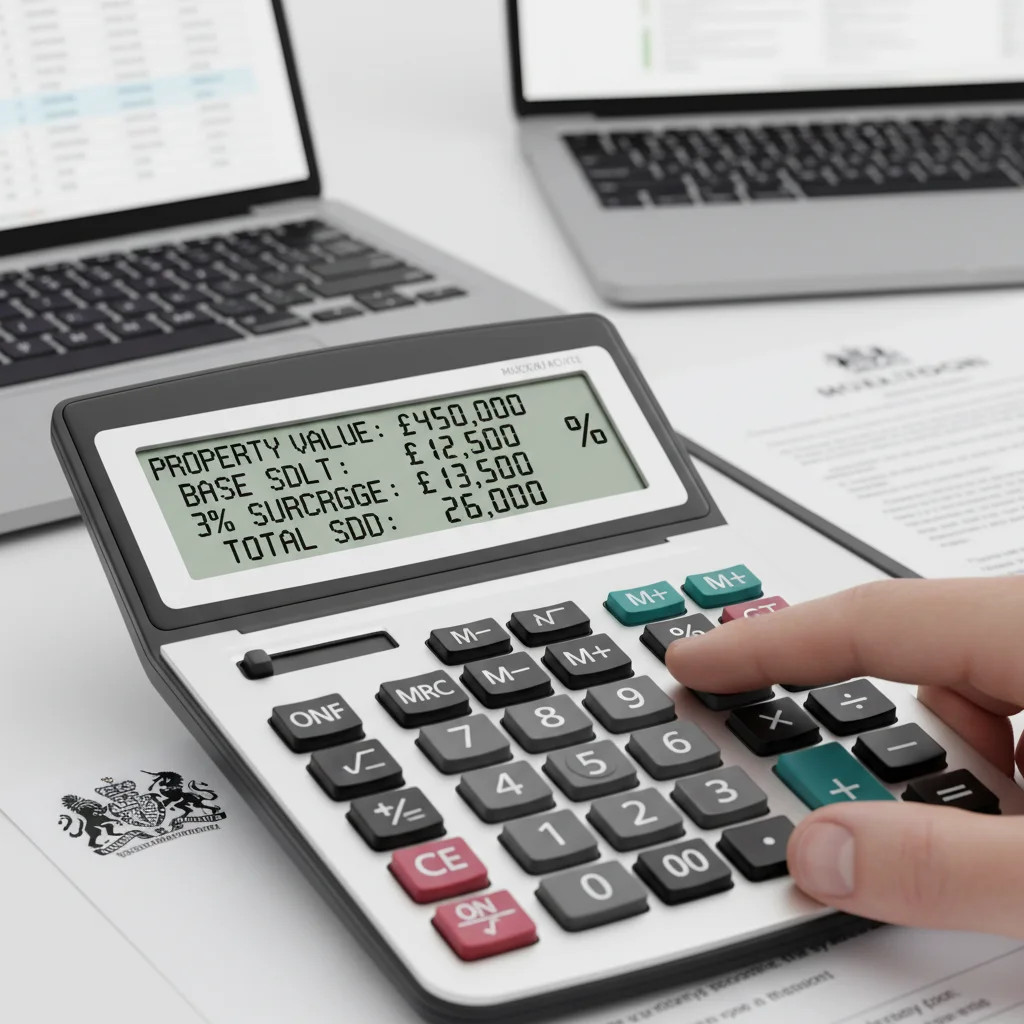
Calculating your Stamp Duty liability with the 3% surcharge requires careful attention to the property’s purchase price and the relevant tax bands. First, you need to determine the standard Stamp Duty rates that would apply to the property’s value. These rates are progressive, meaning different portions of the purchase price are taxed at different percentages. For example, a certain portion might be taxed at 0%, the next at 2%, and so on. Once you have these standard rates, you then add the additional 3% to each applicable band.
Let’s consider a practical example to illustrate this. Suppose you are buying an investment property for £300,000, and you already own your main residence. For the first £250,000, the standard rate is 0%, but with the surcharge, it becomes 3%. For the portion between £250,001 and £925,000, the standard rate is 5%, which becomes 8% with the surcharge. So, for your £300,000 property, you would pay 3% on the first £250,000 and 8% on the remaining £50,000. This significantly increases the total Stamp Duty payable compared to a first-time buyer or someone purchasing their only property.
It’s important to use up-to-date Stamp Duty calculators or consult with a property tax expert, as rates and thresholds can change. These tools and professionals can help you accurately assess the total cost, ensuring no hidden surprises. Remember, the calculation isn’t just about the 3%; it’s about how that 3% integrates with the existing tiered Stamp Duty system, creating a higher overall tax burden for additional property purchases. Accurate calculation is a cornerstone of sound financial planning for any buy-to-let investor.
Key Exemptions and Reliefs for the Surcharge
While the UK buy-to-let surcharge applies broadly, there are specific exemptions and reliefs that can reduce or even negate its impact in certain situations. Understanding these can be crucial for investors, as they might provide opportunities to structure purchases more efficiently. One of the most common reliefs relates to replacing your main residence. If you sell your primary home and buy a new one, but temporarily own both properties because the sale of the old one hasn’t completed yet, you’ll initially pay the surcharge. However, you can claim a refund if you sell your old main residence within three years of buying the new one.
Another important exemption involves properties that are not considered residential, such as commercial properties or mixed-use properties. If a property has a commercial element that is significant enough, it might be exempt from the residential surcharge. This area can be complex, often requiring detailed assessment of the property’s use and layout. Similarly, purchases of caravans, houseboats, or mobile homes are generally exempt from SDLT altogether, and therefore from the surcharge.
Specific Reliefs and Exceptions
Replacing a Main Residence: As mentioned, temporary ownership of two residential properties when replacing your main home can lead to a refund if the old home is sold within three years.
Divorce or Separation: In some cases, transfers of property between spouses or civil partners due to divorce or separation may be exempt.
Inherited Property: If you inherit a property and already own another, the purchase of a new additional property will still attract the surcharge, but the inherited property itself isn’t subject to the surcharge upon inheritance.
Non-Residential or Mixed-Use Properties: Properties with a significant commercial element or those not classified as residential may be exempt.
It’s vital to seek professional advice when considering these exemptions. The rules can be intricate, and misinterpreting them could lead to incorrect tax payments or penalties. A conveyancer or tax advisor specializing in property can provide tailored guidance based on your specific circumstances, ensuring you take advantage of any applicable reliefs while remaining compliant with HMRC regulations.
Strategic Planning for Buy-to-Let Investors
Navigating the complexities of the 3% Stamp Duty surcharge requires strategic planning for any serious buy-to-let investor. Gone are the days when simply acquiring properties was enough; today, a detailed financial strategy is essential to ensure profitability and compliance. One key aspect of this planning involves thoroughly researching the market to identify properties that offer strong rental yields, even after factoring in the additional upfront tax cost. This means looking beyond the headline purchase price and considering the total cost of acquisition, including legal fees, mortgage arrangement fees, and, crucially, the Stamp Duty.
Another strategic consideration is the potential for different ownership structures. While companies and trusts are generally subject to the higher rates, there might be specific scenarios where a corporate structure offers other tax advantages, such as corporation tax rates on rental income, which could offset some of the initial SDLT burden over the long term. However, establishing and managing a limited company for property investment comes with its own set of administrative responsibilities and costs, so this decision should only be made after comprehensive advice from a tax professional and an accountant.
Furthermore, investors should continuously review their portfolios and consider the implications of future property acquisitions. Understanding the long-term impact of the UK buy-to-let surcharge on cash flow and overall return on investment is paramount. This might involve holding properties for longer periods to amortize the initial tax cost, or focusing on areas with higher capital growth potential. Engaging with financial advisors who specialize in property investment can provide invaluable insights, helping you to develop a robust strategy that accounts for all tax implications and market dynamics, ensuring your investment decisions are sound and sustainable in the current regulatory environment.
Frequently Asked Questions
Q1: Does the 3% Stamp Duty surcharge apply to commercial property?
A1: No, the 3% Stamp Duty surcharge specifically applies to the purchase of additional residential properties. Commercial properties or properties with a significant commercial element are generally subject to different Stamp Duty rates and are not affected by this particular surcharge.
Q2: Can I get a refund if I sell my old home after buying a new one with the surcharge?
A2: Yes, if you pay the 3% surcharge because you bought a new main residence before selling your old one, you can claim a refund if you sell your old main residence within three years of buying the new one.
Q3: Are there any specific exemptions for first-time buyers who are also landlords?
A3: First-time buyer relief for Stamp Duty applies only when the property being purchased is the buyer’s *only* residential property. If a first-time buyer immediately purchases a property to let out while also owning another residential property (even if inherited), they would likely be subject to the 3% surcharge.
Q4: How does the surcharge affect married couples or civil partners?
A4: For Stamp Duty purposes, married couples and civil partners are generally treated as a single unit. If either partner already owns a residential property, any new additional residential property purchased by either partner (or jointly) will typically be subject to the 3% surcharge.
Q5: Does the surcharge apply to properties bought through a limited company?
A5: Yes, in most cases, companies purchasing residential properties are subject to the higher rates of Stamp Duty (including the 3% surcharge), regardless of whether they own other properties. There are very limited exceptions for certain types of property developers or businesses.
The 3% Stamp Duty Land Tax surcharge represents a significant financial consideration for anyone looking to invest in additional residential property in the UK. This UK buy-to-let surcharge has fundamentally altered the cost structure for landlords and property investors, making thorough due diligence and strategic financial planning more critical than ever before. Understanding who is affected, how to accurately calculate the increased tax burden, and exploring potential exemptions or reliefs are essential steps in navigating this complex regulatory environment.
While the surcharge adds an extra layer of cost, it doesn’t necessarily deter all investment. Instead, it encourages a more considered and professional approach to property acquisition, prompting investors to seek out properties with stronger fundamentals and to structure their portfolios more efficiently. Engaging with legal and financial professionals is highly recommended to ensure compliance and to optimize your investment strategy. By staying informed and planning meticulously, investors can continue to find opportunities in the UK property market, even with the added Stamp Duty complexities. Adaptability and expert advice are your greatest assets in this evolving landscape.