Claim UK Tax Relief: Unlock £500 in Savings This Year
This comprehensive guide helps you understand and claim UK tax relief, potentially saving you hundreds of pounds. We cover various eligible reliefs, from employment expenses to marriage allowances, providing clear steps to ensure you don't miss out on valuable savings this tax year.
By: [email protected] on August 22, 2026
Última atualização em: agosto 24, 2026
Are you looking to boost your bank balance? Learning how to effectively claim UK tax relief could put hundreds of pounds back into your pocket this year. Many people in the United Kingdom are eligible for various tax reliefs and allowances but simply don’t know about them, or how to apply. This often means leaving money on the table that could otherwise be used for savings, bills, or even a well-deserved treat.
Understanding the different types of tax relief available and the straightforward process to claim them is crucial for any taxpayer. Our comprehensive guide will walk you through the essential steps, highlighting common reliefs and providing practical advice to ensure you don’t miss out. By the end of this article, you’ll be well-equipped to navigate the system and potentially unlock significant savings, making your financial situation a little brighter.
Understanding Your Eligibility for Tax Relief
Many individuals in the UK are eligible for tax relief without even realising it, leading to missed opportunities for savings. Tax relief essentially reduces the amount of tax you have to pay, either by lowering your taxable income or by giving you a direct refund. These reliefs are put in place by the government to support certain activities, expenses, or personal circumstances, and it’s your right to claim them if you qualify. Knowing what you’re entitled to is the first crucial step in getting more money back.
It’s important to remember that eligibility can depend on your employment status, income level, and specific spending patterns throughout the tax year. For example, if you’re employed, you might be able to claim for work-related expenses. If you’re self-employed, a different set of rules and reliefs will apply. Regularly checking your eligibility ensures you’re always making the most of the available allowances and reliefs. Don’t assume you’re not eligible without doing a quick check.
Key Types of Tax Reliefs to Consider
Employment Expenses: This covers costs like professional subscriptions, uniform cleaning, and certain tools or equipment bought for work.
Marriage Allowance: If one partner earns below the Personal Allowance and the other is a basic rate taxpayer, they can transfer a portion of their allowance.
Pension Contributions: Tax relief is usually given on contributions made to a private pension scheme.
Gift Aid: If you’re a UK taxpayer and make donations to charity, the charity can claim an extra 25p for every £1 you donate, and you can claim back the difference if you pay higher rates of tax.
Work from Home Expenses: For those working from home, a fixed amount can be claimed for increased household costs without needing to keep receipts.
Each of these reliefs has specific criteria, and it’s worth exploring them in detail to see if they apply to your situation. The more informed you are, the better your chances of successfully claiming back what you’re owed. This proactive approach can lead to substantial financial benefits over time, helping you to manage your budget more effectively.
Claiming Relief for Employment Expenses
Many employees incur costs directly related to their jobs that can be eligible for tax relief. These aren’t just minor expenses; they can add up significantly over a year, making a noticeable difference to your take-home pay. HMRC understands that some work-related spending is unavoidable, and they have provisions to help you reclaim tax on these outlays. It’s not about trying to ‘get one over’ on the tax system, but rather utilising the allowances designed to support working individuals.
To successfully claim for employment expenses, meticulous record-keeping is absolutely vital. You’ll need to demonstrate to HMRC that the expenses were incurred ‘wholly, exclusively, and necessarily’ for your job. This means the item or service was essential for you to perform your duties and wasn’t for personal use. Keeping receipts, invoices, and a detailed log of dates and reasons for expenditure will make your claim much smoother and more likely to be approved. Without proper documentation, your claim might be rejected.
Common examples of reclaimable employment expenses include professional membership fees required for your job, the cost of washing a uniform that your employer provides and expects you to clean, and necessary tools or specialist equipment you’ve bought yourself. Travel expenses for business trips (excluding your regular commute) can also be claimed. For those who work from home, there’s a simplified allowance available, or you can claim for the actual increased costs if they’re higher and you have evidence. It’s always a good idea to check the specific rules for each type of expense, as they can sometimes vary.
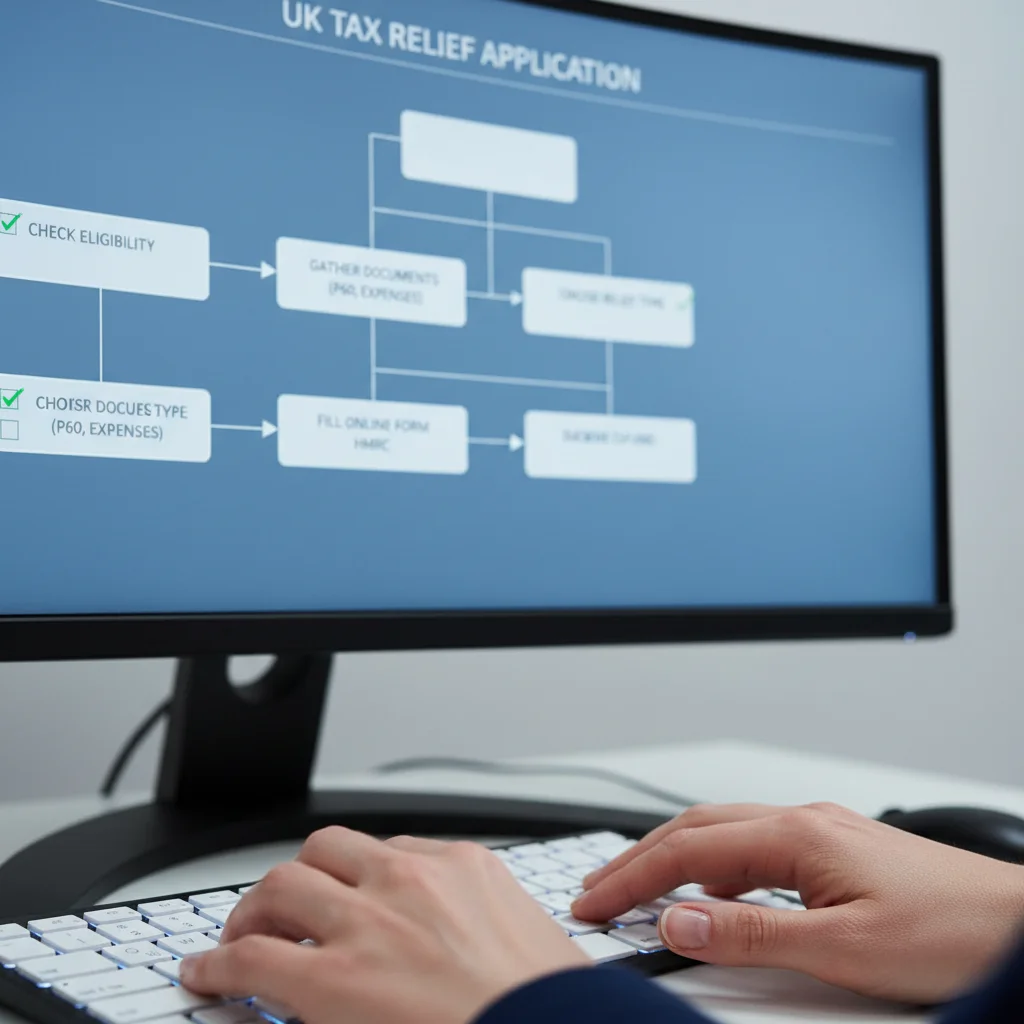
The process for claiming these expenses usually involves either updating your tax code or submitting a P87 form online or by post. If the amount you’re claiming is relatively small and consistent each year, HMRC might adjust your tax code so you pay less tax throughout the year. For larger or one-off claims, a P87 is the standard route. Remember, you can typically claim back for the past four tax years, so don’t delay in reviewing your old expenses.
Understanding and acting on these employment expense reliefs is a straightforward way to reduce your tax burden. It’s about ensuring you’re not out of pocket for costs that are integral to your ability to earn an income. Taking the time to gather your records and submit a claim can result in a welcome boost to your finances.
Maximising Your Marriage Allowance Claim
The Marriage Allowance is a fantastic but often overlooked tax relief that can save eligible couples hundreds of pounds each year. It allows one partner to transfer a portion of their unused Personal Allowance to their spouse or civil partner. This is particularly beneficial for couples where one person earns below the personal allowance threshold (meaning they don’t use all of their tax-free income allowance) and the other is a basic rate taxpayer. It’s a simple concept designed to help families keep more of their earnings.
To qualify, the lower earner must have an income below the Personal Allowance, which is currently £12,570 for most people. The higher earner must be a basic rate taxpayer, meaning their income falls between £12,571 and £50,270. If these conditions are met, the lower earner can transfer 10% of their Personal Allowance, which is £1,260 for the 2023/24 tax year. This transfer then reduces the higher earner’s taxable income by the same amount, leading to a tax saving of up to £252 per tax year.
The application process for the Marriage Allowance is relatively straightforward and can be done online via the GOV.UK website. It’s the lower earner who needs to make the claim, as they are the one transferring their allowance. Once approved, the tax code of the higher earner will be adjusted, and they will pay less tax from that point onwards. If you’re claiming for previous tax years, you’ll receive a lump sum refund. This can be a significant amount, as you can backdate your claim for up to four previous tax years, potentially receiving over £1,000 in total.
It’s worth noting that even if circumstances change, such as an increase in the lower earner’s income, you can easily cancel the Marriage Allowance. However, for many couples, it represents a consistent and valuable saving. Don’t miss out on this opportunity to boost your household income simply because you weren’t aware of it. A quick check of your and your partner’s income can confirm if you are eligible and set you on the path to claiming this beneficial tax relief.
Claiming Tax Relief on Pension Contributions
Saving for retirement is a critical financial goal for many, and the government offers significant tax relief on pension contributions to encourage this. This means that for every pound you put into a private pension, the government effectively tops it up, making your savings grow faster. Understanding how this relief works is key to maximising your retirement fund and reducing your current tax bill. It’s a powerful incentive that should not be overlooked when planning your finances.
For most people, especially basic rate taxpayers, pension providers automatically claim 20% tax relief at source. This means that if you contribute £80 to your pension, your provider adds another £20, making your total contribution £100. You don’t usually need to do anything extra to receive this basic rate relief. However, if you’re a higher or additional rate taxpayer, you’re eligible for even more relief, and you’ll need to claim this additional amount yourself.
Higher rate taxpayers can claim an extra 20% relief, and additional rate taxpayers can claim a further 25%. This additional relief is usually claimed through your annual Self Assessment tax return. If you don’t complete a Self Assessment, you can contact HMRC directly to inform them of your pension contributions. They will then adjust your tax code or send you a refund. Keeping records of all your pension contributions is essential for this process, as you’ll need to provide accurate figures.
There are limits to how much you can contribute to a pension each year while still receiving tax relief. This is known as the annual allowance, which is currently £60,000 for most people, or 100% of your earnings, whichever is lower. There’s also a lifetime allowance, though this has recently seen changes. Exceeding these allowances can lead to tax charges, so it’s important to be aware of them. Consulting a financial advisor can be particularly helpful if you have substantial pension savings or complex income streams, ensuring you navigate these rules effectively and continue to claim UK tax relief on your contributions.
Navigating the Self Assessment System for Refunds
For many, particularly the self-employed, those with complex income, or individuals needing to claim specific reliefs, the Self Assessment system is the primary method for interacting with HMRC and claiming tax refunds. While it might seem daunting at first glance, understanding its core principles can empower you to accurately report your income and expenses, ensuring you pay the correct amount of tax and claim all eligible reliefs. It’s designed to be a comprehensive overview of your financial year.
The first step in navigating Self Assessment is to determine if you need to register. You’ll typically need to register if you’re self-employed, a company director, receive income from renting out property, or have significant untaxed income. Once registered, HMRC will send you a Unique Taxpayer Reference (UTR) number, which you’ll need to complete your tax return. The deadline for online submissions is usually 31 January following the end of the tax year, with a paper deadline of 31 October.
When completing your Self Assessment, you’ll report all your income from various sources, such as employment, self-employment, property, interest, and dividends. Crucially, this is also where you declare your expenses and claim any applicable tax reliefs. This could include business expenses for the self-employed, pension contributions (especially for higher-rate relief), and other allowances not automatically applied through your PAYE tax code. Accurate record-keeping throughout the year is paramount to make this process as smooth as possible.
If you’ve overpaid tax during the year, perhaps due to an incorrect tax code or because you’ve claimed eligible reliefs, the Self Assessment system will calculate your refund. This refund will then typically be paid directly into your nominated bank account. It’s vital to double-check all figures before submitting your return, as errors can lead to delays or even penalties. If you’re unsure, HMRC provides guidance, and professional tax advisors can offer invaluable assistance. Using this system correctly is an effective way to claim UK tax relief and ensure your tax affairs are in order, potentially resulting in a welcome refund.
Frequently Asked Questions
What is the Personal Allowance?
The Personal Allowance is the amount of income you can earn each tax year before you start paying Income Tax. For the 2023/24 tax year, it is £12,570 for most people. Any income below this threshold is tax-free.
How far back can I claim tax relief?
You can generally claim tax relief for the past four tax years. This means if you discover you were eligible for a relief in a previous year, you still have an opportunity to claim it back.
Do I need receipts for all my claims?
Yes, for most expense-based claims, you will need to keep accurate records, including receipts, invoices, and bank statements, as proof. HMRC may ask for these to verify your claims.
What happens if I make a mistake on my tax claim?
If you realise you’ve made a mistake on a tax claim or Self Assessment return, you should contact HMRC as soon as possible to amend it. Correcting errors promptly can help avoid potential penalties.
Can I claim tax relief if I am self-employed?
Absolutely. Self-employed individuals can claim a wide range of business expenses, such as office costs, travel, and professional fees, through their Self Assessment tax return, effectively reducing their taxable profits.
Successfully navigating the world of UK tax relief can lead to significant financial benefits, putting hundreds of pounds back into your wallet each year. By understanding the various allowances and reliefs available, from employment expenses to the Marriage Allowance and pension contributions, you empower yourself to make informed financial decisions. The key lies in being proactive, maintaining thorough records, and knowing where to look for eligibility.
Don’t let the complexity of tax deter you from claiming what you’re rightfully owed. HMRC provides clear guidance, and the processes are often simpler than many people imagine. Taking the time to review your circumstances, gather your documents, and submit your claims can result in a welcome boost to your savings or disposable income. Start exploring your eligibility today and take the first step towards unlocking your potential tax savings. Every pound you claim back is a pound you keep, contributing to a more secure and comfortable financial future.
Peter B holds a degree in Journalism and has 5 years of experience covering U.S. economic policy, labor markets, and financial news. He writes data-driven news content on topics like inflation, interest rates, and employment trends.