UK Stamp Duty Land Tax Thresholds: Avoid Property Purchase Costs
Understanding UK Stamp Duty Land Tax Thresholds is crucial for property buyers. This guide breaks down current rates, important exemptions, and offers practical advice to help you manage costs and avoid surprises when purchasing a property in the UK.
By: [email protected] on August 22, 2026
Última atualização em: agosto 24, 2026
Your Guide to the Latest UK Stamp Duty Land Tax Thresholds: Avoid Unexpected Costs on Property Purchases
Navigating the property market in the UK can feel like a maze, especially when it comes to understanding the financial obligations involved. One of the most significant costs you’ll encounter, beyond the property price itself, is Stamp Duty Land Tax (SDLT). Keeping abreast of the latest UK Stamp Duty Thresholds is absolutely critical for anyone looking to buy property, whether it’s your first home, an investment, or a new family residence.
This comprehensive guide aims to demystify SDLT, providing you with a clear understanding of current rates, important exemptions, and practical strategies to help you avoid unexpected costs. We’ll break down the complexities, ensuring you’re well-prepared for your property purchase journey and can budget effectively.
Understanding the Current UK Stamp Duty Thresholds and Rates
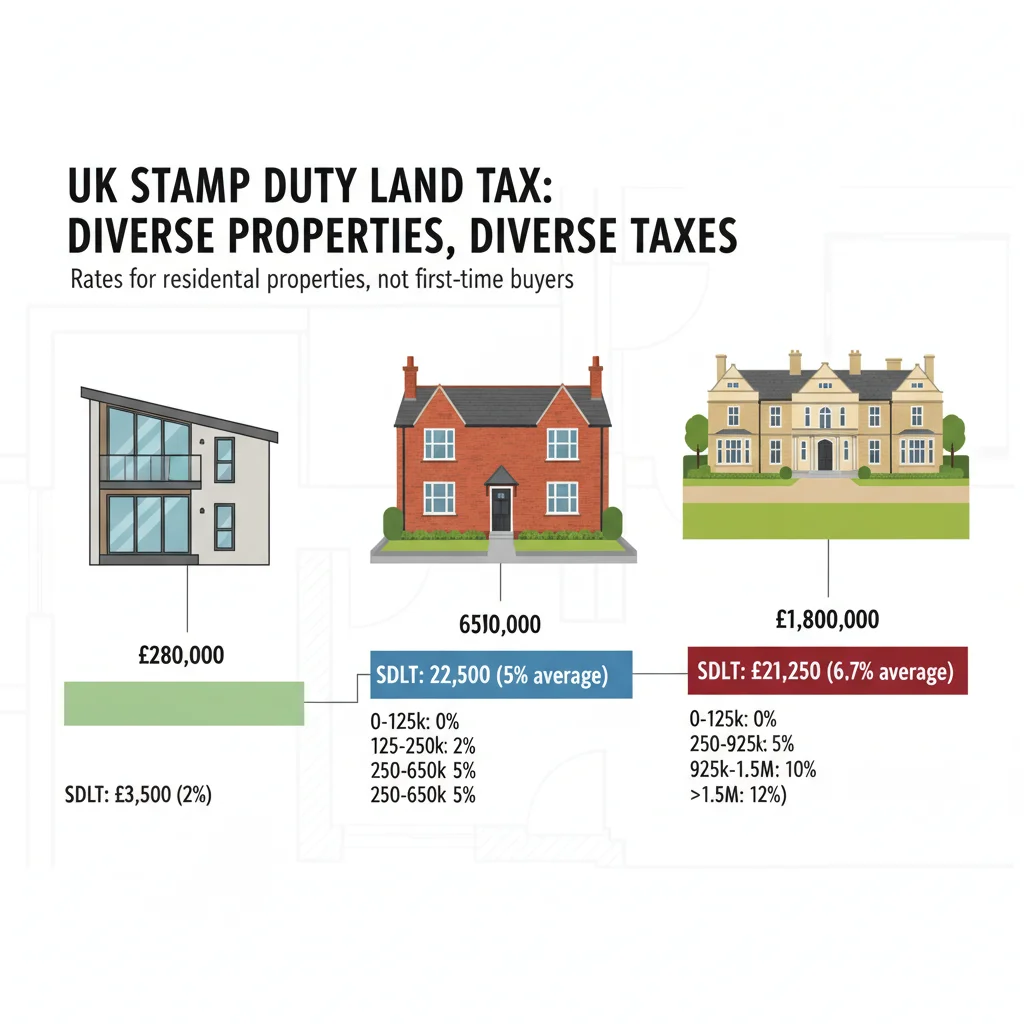
Stamp Duty Land Tax (SDLT) is a tax paid when you buy a property or land in England and Northern Ireland. The amount you pay depends on the purchase price of the property and whether you’re a first-time buyer, buying an additional property, or a non-UK resident. The system is tiered, meaning you only pay the higher rate on the portion of the property price that falls within that band, not on the entire amount. This progressive structure is designed to make the tax fairer across different property values.
Currently, for residential properties, there’s a tax-free threshold, above which different rates apply. It’s important to remember that these thresholds and rates can be subject to change based on government policy, so staying informed is key. The rates can significantly impact your overall budget, making it essential to factor SDLT into your financial planning from the very beginning of your property search. Understanding these core principles is the first step towards accurately calculating your potential tax liability.
For most residential property purchases, the current standard UK Stamp Duty Thresholds and rates are applied based on the purchase price. These rates are crucial for every buyer to be aware of, as they directly influence the total cost of acquiring property. It’s not just about the price tag of the house; it’s also about the additional government levies. Miscalculating this can lead to significant financial strain or delays in your property transaction. Therefore, familiarizing yourself with these figures is a foundational step in your property buying process.
First-Time Buyer Relief: A Key Advantage
First-time buyers in the UK often benefit from significant relief on Stamp Duty Land Tax, a measure designed to help more people get onto the property ladder. This relief means that if you’re purchasing your first home, you might pay less SDLT or even none at all, depending on the property’s purchase price. To qualify as a first-time buyer, you must not have owned any residential property in the UK or anywhere else in the world. This includes property inherited or received as a gift, even if you never lived in it. The property you are buying must also be intended as your main residence, not an investment or buy-to-let.
The relief provides a complete exemption from SDLT on properties up to a certain value. For properties above this initial threshold but below a higher cap, a reduced rate of SDLT applies. This can translate into substantial savings, making homeownership more accessible for many individuals and couples. It’s a critical aspect to consider if you’re entering the property market for the first time, as it directly impacts your upfront costs. Ensuring you meet all the criteria for first-time buyer relief is paramount to taking advantage of this beneficial scheme.
Eligibility Criteria for First-Time Buyer Relief
You must be buying your only or main home.
You must not have owned any residential property before, anywhere in the world.
If buying with someone else, both of you must be first-time buyers.
The property’s purchase price must fall within the specified limits for relief.
It is important to declare your first-time buyer status correctly to your solicitor, who will handle the SDLT submission on your behalf. Providing accurate information ensures you receive the correct relief and avoid any potential penalties from HMRC. This relief is a valuable incentive, but understanding its specific conditions is key to leveraging it effectively in your property purchase.
Additional Property Surcharge: What You Need to Know
When purchasing an additional residential property in the UK, such as a buy-to-let investment or a second home, a higher rate of Stamp Duty Land Tax generally applies. This surcharge is an extra percentage added on top of the standard SDLT rates and was introduced to help cool the housing market and ensure a fairer distribution of properties. It significantly increases the overall cost of acquiring an additional property, so it’s crucial to factor this into your financial calculations from the outset. Many buyers are caught off guard by this additional cost, underestimating its impact on their budget.
This higher rate applies to individuals purchasing a second home, as well as to companies and trusts buying residential property. There are some specific circumstances where the higher rates might not apply, such as if you are replacing your main residence, even if you own another property temporarily. However, these exceptions often come with strict conditions and time limits for selling your previous main home. It’s vital to understand these nuances to avoid unexpected financial burdens when expanding your property portfolio.
The additional property surcharge is levied on the entire purchase price of the property, not just the portion above a certain threshold, which makes it a substantial cost. For example, if you already own a property and are buying another, you will likely pay the additional percentage on the full value of the new purchase. This can make a significant difference to the affordability of your investment. Always consult with a solicitor or tax advisor to understand how these rules apply to your specific situation, as getting it wrong can lead to considerable financial penalties. Proper planning is essential to navigate these extra costs effectively.
Non-UK Resident Surcharge and Other Exemptions
Beyond the standard rates and the additional property surcharge, non-UK residents purchasing residential property in England and Northern Ireland face an extra percentage of Stamp Duty Land Tax. This surcharge was introduced to help manage demand in the housing market and ensure a level playing field for UK residents. It applies on top of any other applicable SDLT rates, including the higher rates for additional properties. This means that a non-UK resident buying a second home could face a cumulative SDLT charge that is significantly higher than what a first-time buyer would pay.
Defining “non-UK resident” for SDLT purposes has specific criteria related to the number of days spent in the UK in the 12 months leading up to the purchase. It’s not simply about your nationality or where you primarily live. This distinction is crucial, as misinterpreting your residency status could lead to incorrect tax payments and potential penalties. Therefore, it’s essential for international buyers to seek expert advice to determine their exact SDLT obligations before committing to a property purchase in the UK.
While the focus is often on what you have to pay, it’s equally important to be aware of certain exemptions and reliefs that might apply to your situation, beyond first-time buyer relief. For instance, some property transfers, such as those made under a will or as a gift, may be exempt from SDLT. Transfers between spouses or civil partners are also often exempt. Certain types of commercial properties or mixed-use properties might have different SDLT rules altogether. Understanding these specific exemptions can potentially save you a considerable amount, reinforcing the need for thorough research and professional guidance tailored to your individual circumstances.
Practical Tips to Avoid Unexpected SDLT Costs
Avoiding unexpected Stamp Duty Land Tax costs requires careful planning and a thorough understanding of the rules. One of the most effective strategies is to get a clear, professional calculation of your potential SDLT liability early in the process. Your solicitor will typically provide this, but it’s wise to independently verify or use online calculators to get an estimate. This proactive approach helps you budget accurately and prevents any last-minute surprises that could derail your purchase. Remember, SDLT is a significant upfront cost that needs to be accounted for alongside your deposit and other fees.
Another crucial tip is to be completely transparent with your legal team about your property history and residency status. Even minor details, such as owning a small share in an overseas property or having inherited a property many years ago, can impact your SDLT liability, particularly regarding first-time buyer relief or the additional property surcharge. Full disclosure ensures your solicitor can correctly advise you and apply the appropriate rates and exemptions, safeguarding you from future complications with HMRC. Honesty in these matters is always the best policy.
Finally, keep an eye on government announcements regarding Stamp Duty Land Tax. Rates and thresholds can change, sometimes with little notice, especially during budget statements. Subscribing to property news alerts or checking official government websites regularly can help you stay informed of any potential alterations that might affect your purchase. Being aware of these changes allows you to adapt your plans accordingly and continue to navigate the UK Stamp Duty Thresholds with confidence, ensuring a smoother and more cost-effective property transaction. Preparation is your best defence against unforeseen expenses.
Frequently Asked Questions
What is Stamp Duty Land Tax (SDLT)?
SDLT is a tax paid when you buy a property or land in England and Northern Ireland. The amount you pay depends on the purchase price and your individual circumstances, such as whether you are a first-time buyer or purchasing an additional property. It’s an essential part of the cost of buying property.
How do I know if I’m a first-time buyer for SDLT purposes?
You are considered a first-time buyer if you have never owned residential property in the UK or anywhere else in the world, and you intend to occupy the property as your main residence. If buying jointly, all purchasers must meet this criterion to qualify for relief.
When do I pay Stamp Duty Land Tax?
SDLT is usually paid within 14 days of the completion of your property purchase. Your solicitor will typically handle the calculation and submission of the SDLT return to HMRC on your behalf, ensuring it’s paid on time.
Does SDLT apply to all property purchases?
SDLT generally applies to residential property purchases over a certain threshold. However, there are specific exemptions and reliefs, such as certain transfers between spouses, gifts, or properties below the minimum taxable value. Commercial properties also have different rules.
What happens if I don’t pay SDLT on time?
If you fail to pay SDLT within the 14-day deadline, you may incur penalties and interest charges from HMRC. It’s crucial to ensure your solicitor submits the return and payment promptly to avoid these additional costs.
Understanding the UK Stamp Duty Thresholds is not just about knowing the rates; it’s about informed decision-making and avoiding unexpected financial burdens. This guide has aimed to illuminate the complexities of Stamp Duty Land Tax, from standard rates and valuable first-time buyer relief to the additional property surcharge and non-UK resident considerations. By grasping these key aspects, property buyers can approach their purchase with greater confidence and a clearer financial picture.
The property market constantly evolves, and with it, the rules and regulations surrounding SDLT. Staying updated through official government channels and consulting with legal professionals are indispensable steps. Proactive planning, transparent communication with your solicitor, and a vigilant eye on policy changes will ensure you navigate the property buying process smoothly. Don’t let unexpected SDLT costs deter you; instead, empower yourself with knowledge. Take the time to understand these thresholds thoroughly, budget effectively, and embark on your property ownership journey with peace of mind. Your dream home or investment property awaits, and being well-prepared for SDLT is a crucial part of making that dream a reality.
Peter B holds a degree in Journalism and has 5 years of experience covering U.S. economic policy, labor markets, and financial news. He writes data-driven news content on topics like inflation, interest rates, and employment trends.