National Living Wage Increase: Your Take-Home Pay & Budget
This article explores the critical 1.25% increase in the National Living Wage, detailing its direct effects on your take-home pay. Discover practical strategies to adjust your household budget and navigate the changes, ensuring your financial well-being in the evolving economic landscape.
By: [email protected] on August 22, 2026
Última atualização em: agosto 24, 2026
Critical Update: How the 1.25% Increase in National Living Wage Impacts Your Take-Home Pay and Budget
The recent 1.25% National Living Wage increase is a significant development that will directly affect millions of workers across the country. This adjustment is designed to help ensure that those in the lowest-paid jobs receive a fairer income, reflecting the rising cost of living and contributing to a more equitable economy. For many, this means a welcome boost to their earnings, providing a bit more breathing room in their monthly finances. However, understanding the full scope of this change, particularly how it translates to your take-home pay and what it means for your household budget, is crucial for effective financial planning.
While an increase in wages is generally positive, the actual amount you see in your bank account can be influenced by various factors, including taxes and national insurance contributions. This article will break down these complexities, offering clear insights into how the National Living Wage increase impacts your personal finances. We’ll explore practical steps you can take to adapt your budget, maximize the benefits of this pay rise, and ensure your financial health remains robust in the face of ongoing economic shifts. Being prepared and informed is key to making the most of these important changes.
Understanding the National Living Wage Increase
The National Living Wage (NLW) is the minimum hourly rate that workers aged 23 and over in the UK are legally entitled to receive. This rate is reviewed annually by the government, based on recommendations from the Low Pay Commission, an independent body that advises on the NLW and National Minimum Wage. The recent 1.25% increase reflects ongoing efforts to ensure that the lowest-paid workers can maintain a reasonable standard of living amidst economic changes. This adjustment aims to balance the needs of employees with the capacity of businesses to absorb higher labor costs, striving for a sustainable economic environment for everyone.
For those earning at or around the previous NLW, this 1.25% hike translates into a direct rise in their gross hourly pay. While it might seem like a modest percentage, over the course of a full working year, it can add up to a noticeable difference in annual income. This increase is particularly important for individuals and families who rely heavily on the NLW to cover their essential living expenses. It can provide a much-needed buffer against inflation and rising costs, potentially reducing financial strain and offering a greater sense of security. Understanding the specific new hourly rate and how it applies to your age and working hours is the first step in calculating your new gross income.
It is important to remember that the NLW is distinct from the National Minimum Wage (NMW), which applies to workers under 23. While both are minimum pay rates, the NLW is set at a higher level, reflecting the government’s aim for older workers to earn a wage that better supports their living costs. The Low Pay Commission’s recommendations consider a wide range of economic indicators, including inflation, wage growth, and employment levels, to arrive at a figure that is both fair to workers and manageable for businesses. This comprehensive approach ensures that the NLW remains a relevant and impactful policy for improving living standards across the UK.
Calculating Your New Take-Home Pay
Translating the National Living Wage increase into your actual take-home pay involves more than just multiplying your new hourly rate by your working hours. The gross pay increase will be subject to deductions such as income tax and National Insurance contributions. These deductions are calculated based on your total earnings, so a higher gross wage will generally mean slightly higher contributions to these statutory payments. Understanding these deductions is crucial because they determine the net amount you receive in your bank account, which is what you truly have available for spending and saving.
To get a clear picture, you’ll need to consider your personal tax code and any other deductions, such as pension contributions or student loan repayments. Each of these can impact the final figure. For instance, if your pay rise moves you into a higher tax bracket for a portion of your income, that specific portion will be taxed at the new, higher rate. Similarly, your National Insurance contributions are percentage-based, so they will also increase in line with your higher earnings. Many online calculators can help you estimate your new take-home pay by inputting your gross wage, tax code, and other relevant details. It’s a good idea to use these tools to get an approximate figure before your first pay slip with the new rate arrives.
Beyond statutory deductions, some employers might also deduct for things like workplace benefits, union fees, or specific salary sacrifice schemes. These non-statutory deductions also play a role in the final take-home amount. It’s always advisable to review your payslip carefully once the new rate comes into effect. Compare your new net pay with your previous net pay to understand the exact financial uplift. Don’t just focus on the gross increase; the net figure is what truly matters for your day-to-day budgeting and financial planning. Being proactive in understanding these calculations will empower you to manage your finances more effectively.
Adjusting Your Household Budget
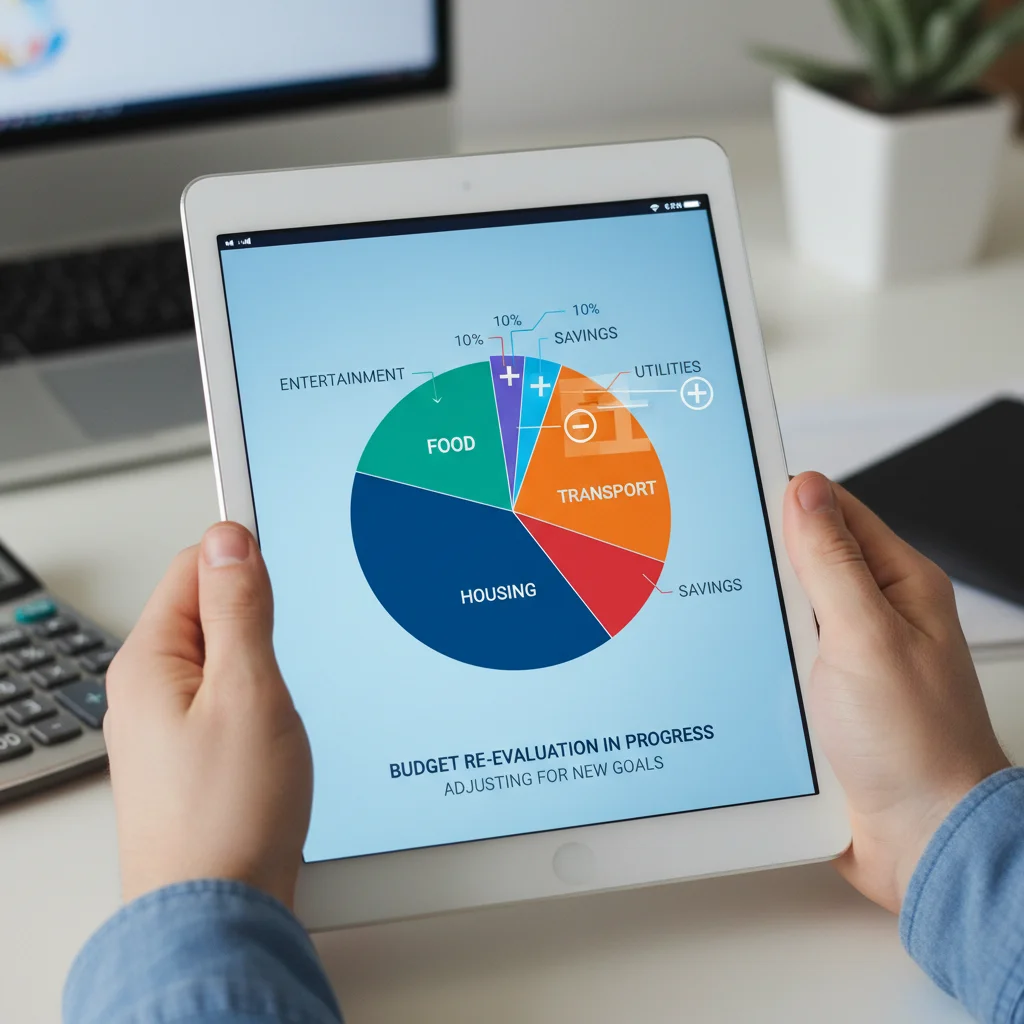
With an increase in your take-home pay from the National Living Wage, it’s an ideal time to revisit and adjust your household budget. Even a small increase can make a significant difference, especially if you’ve been operating on a tight budget. The goal is not just to spend the extra money, but to strategically allocate it in a way that improves your financial stability and helps you achieve your goals. This might involve re-evaluating your current spending habits, identifying areas where you can make improvements, or allocating funds towards long-term objectives.
Key Areas for Budget Adjustment:
Emergency Savings: If you don’t have an emergency fund, or if yours is insufficient, direct a portion of your increased pay towards building or topping it up. A robust emergency fund provides a crucial safety net for unexpected expenses like car repairs or medical emergencies, preventing you from falling into debt.
Debt Reduction: Consider using the extra income to pay down high-interest debts, such as credit card balances or personal loans. Reducing debt can free up more of your income in the long run and significantly improve your financial health, saving you money on interest payments.
Essential Expenses: Assess if your essential expenses, like groceries, utilities, or transport, have increased. The pay rise can help absorb these higher costs, preventing them from straining your budget further. Ensure you’re still getting the best deals on these services.
Future Planning: Allocate some funds towards future goals, such as saving for a deposit on a home, retirement, or a child’s education. Even small, consistent contributions can grow substantially over time, thanks to the power of compounding.
Discretionary Spending: While it’s tempting to increase discretionary spending, try to be mindful. A small portion can be enjoyed, but prioritize your financial well-being first.
By consciously directing your increased earnings, you can transform a modest pay rise into a powerful tool for financial improvement. This proactive approach ensures that the National Living Wage increase truly benefits your long-term financial outlook rather than simply being absorbed by everyday spending without a clear purpose.
Navigating Inflation and Cost of Living
While the National Living Wage increase is a positive step, it’s important to view it within the broader context of inflation and the rising cost of living. The price of everyday goods and services, from groceries to energy bills, has been steadily climbing. This means that while your gross earnings have gone up, the purchasing power of that money might not have increased as much as you’d hope. Understanding this dynamic is key to realistic financial planning and preventing a sense of false security from the pay rise.
Inflation erodes the value of money over time. If the rate of inflation is higher than your wage increase, your real-term purchasing power may actually decrease, even with a nominal pay rise. This is why it’s so important to not only track your income but also monitor your expenses closely. Being aware of where your money is going and how much essential items are costing helps you make informed decisions about your budget. For example, if food prices have gone up significantly, you might need to adjust your grocery shopping habits or look for more affordable alternatives to stretch your budget further.
To effectively navigate the challenges posed by inflation, consider adopting strategies that maximize the value of your money. This could involve smart shopping, such as buying in bulk when items are on offer, using loyalty programs, or cooking more meals at home rather than eating out. Reviewing your utility providers and insurance policies regularly to ensure you’re getting the most competitive rates can also save you a significant amount over the year. The National Living Wage increase provides an opportunity to implement these money-saving habits, ensuring that the extra income genuinely contributes to improving your financial situation rather than simply being swallowed by rising costs. It’s about being strategic and proactive.
Long-Term Financial Planning Strategies
Beyond immediate budgeting adjustments, the National Living Wage increase offers a valuable opportunity to consider your long-term financial planning. Thinking about the future, even with a modest income, can significantly improve your financial security and independence over time. This involves setting clear financial goals, understanding different savings and investment options, and consistently working towards them. It’s about building a financial foundation that can withstand life’s uncertainties and help you achieve your aspirations, from buying a home to enjoying a comfortable retirement.
One effective strategy is to automate your savings. As soon as your increased National Living Wage hits your bank account, have a portion of it automatically transferred to a separate savings account. This ‘pay yourself first’ approach ensures that you’re consistently saving without having to consciously decide each month. Even a small, regular contribution can grow substantially over the years. Consider different types of savings accounts, such as an ISA (Individual Savings Account), which offers tax-free interest, making your money work harder for you. Exploring these options can provide greater returns than a standard current account.
Another crucial element of long-term planning is understanding your pension options. If your employer offers a workplace pension scheme, ensure you are contributing, especially if they match your contributions. This is essentially free money and significantly boosts your retirement savings. Even if you’re not planning for retirement yet, starting early allows your investments more time to grow. Regularly reviewing your financial goals and progress will help you stay on track and make adjustments as your circumstances change. The National Living Wage increase should serve as a catalyst to solidify or start your journey towards greater financial resilience and independence.
Frequently Asked Questions
Who is eligible for the National Living Wage?
The National Living Wage applies to all workers aged 23 and over in the UK. If you are 22 or younger, you are entitled to the National Minimum Wage, which has different rates depending on your age group.
How often is the National Living Wage reviewed?
The National Living Wage is reviewed annually by the government, based on recommendations from the independent Low Pay Commission. Changes typically come into effect at the start of the new financial year, usually in April.
Will my take-home pay increase by the full 1.25%?
Not necessarily. While your gross hourly pay will increase by 1.25%, your take-home pay (net pay) will be slightly less due to deductions for income tax and National Insurance contributions, which will also increase in line with your higher earnings.
What should I do if my employer doesn’t pay the correct National Living Wage?
If you believe your employer is not paying you the correct National Living Wage, you should first try to discuss it with them. If that doesn’t resolve the issue, you can contact ACAS (Advisory, Conciliation and Arbitration Service) or HMRC for advice and support.
How can I best use the extra money from the wage increase?
It’s recommended to prioritize building an emergency fund, paying down high-interest debt, or increasing savings for long-term goals. While it’s tempting to increase spending, strategic allocation can significantly improve your financial stability.
The 1.25% National Living Wage increase represents a crucial adjustment aimed at supporting workers and addressing the evolving economic landscape. For millions, this means a tangible boost to their gross earnings, offering a welcome opportunity to strengthen personal finances. However, the true impact on your take-home pay requires a careful understanding of tax and National Insurance deductions, which will influence the final net amount you receive. It’s not just about the gross increase, but how much more you actually have available to spend or save after these essential contributions.
This pay rise also serves as an opportune moment to critically review and adjust your household budget. By strategically allocating any extra income towards building emergency savings, paying down debt, or contributing to long-term financial goals, you can maximize the benefits of this increase. Being mindful of inflation and the rising cost of living is equally important, ensuring that your increased purchasing power is managed effectively. Embracing proactive financial planning, from automating savings to understanding pension options, will empower you to build greater financial resilience. Ultimately, making informed decisions now will help you navigate economic shifts and secure a more stable financial future for yourself and your family.
Peter B holds a degree in Journalism and has 5 years of experience covering U.S. economic policy, labor markets, and financial news. He writes data-driven news content on topics like inflation, interest rates, and employment trends.