Housing Benefit Updates: Understanding the 2.9% LHA Adjustment
This article explores the recent 2.9% Local Housing Allowance (LHA) rate adjustment and its implications for renters receiving Housing Benefit. Understand how these updates might affect your housing support and what steps you can take to navigate the changes effectively.
By: pedropadm2025@gmail.com on August 22, 2026
Última atualização em: agosto 24, 2026
Recent Housing Benefit updates have brought significant changes, particularly with the 2.9% Local Housing Allowance (LHA) rate adjustment. For many renters across the UK, understanding these adjustments is crucial for managing their housing costs and ensuring continued support. This change, while seemingly modest, can have a tangible impact on what individuals and families receive to help cover their rent.
The LHA rates are a critical component of the Housing Benefit system, determining the maximum amount of financial assistance available to private renters. These rates are set based on local market rents and the number of bedrooms a household needs. When adjustments occur, like the recent 2.9% increase, it’s essential for claimants to know how their entitlements might shift and what steps they may need to take.
Decoding the 2.9% LHA Rate Adjustment
The recent 2.9% Local Housing Allowance (LHA) rate adjustment represents a change in the maximum amount of Housing Benefit or Universal Credit housing element that private renters can receive. This percentage increase is applied to the existing LHA rates, which are determined by the Valuation Office Agency (VOA) based on local market rents. Essentially, it means that for many areas, the cap on housing support has seen a slight uplift, aiming to provide a bit more assistance in an environment of rising rental costs.
However, it’s important to understand that this adjustment doesn’t automatically mean everyone’s Housing Benefit will increase by exactly 2.9%. The actual amount an individual receives still depends on various factors, including their income, savings, household composition, and the specific LHA rate applicable to their area and property size. The 2.9% is an adjustment to the *maximum* rate, not a universal increase across all claims.
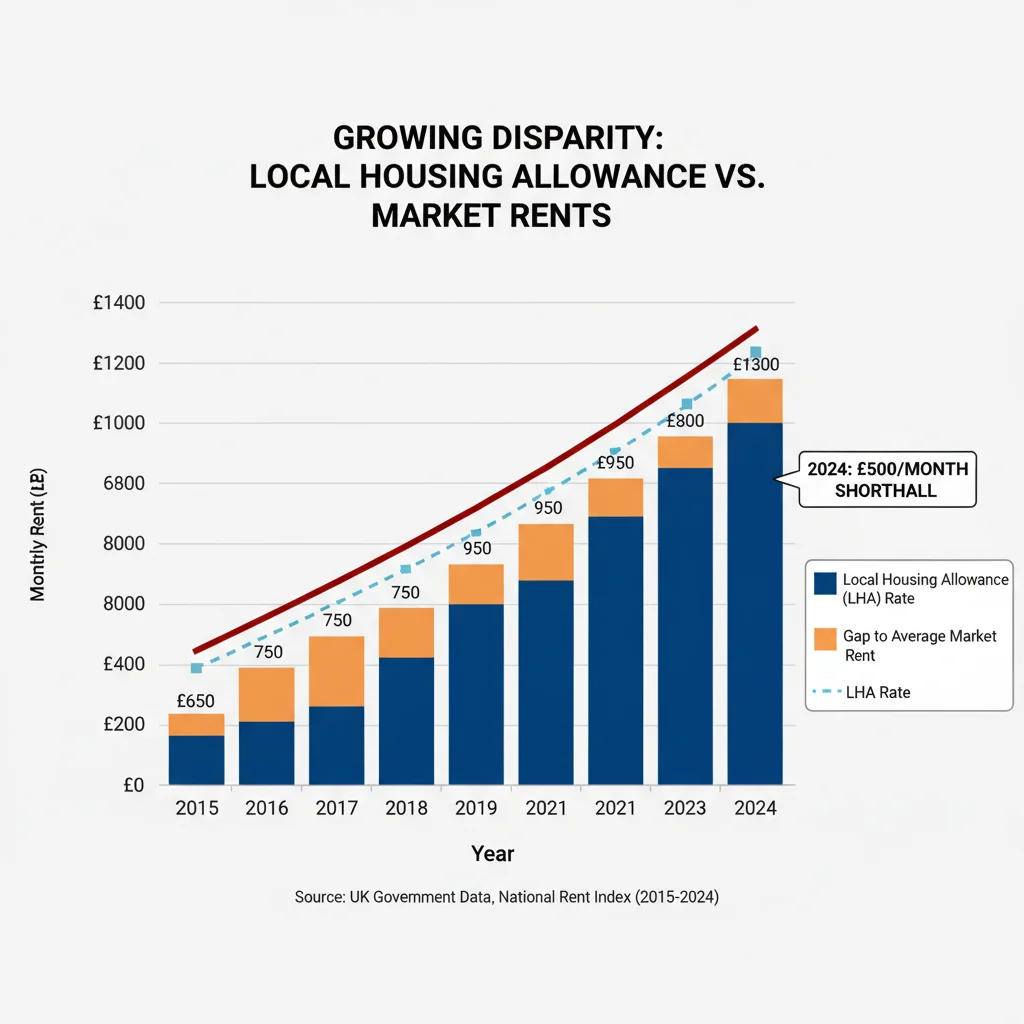
This adjustment is a response to the ongoing pressures in the private rental market, where rents have consistently climbed, often outstripping the growth in LHA rates in previous years. While any increase is generally welcomed by renters, the effectiveness of this 2.9% adjustment in truly bridging the gap between LHA rates and actual market rents will vary significantly depending on the local housing market dynamics. For some, it might offer a much-needed boost, while for others, the disparity might remain substantial.
Who Benefits from the LHA Rate Adjustment?
The LHA rate adjustment primarily benefits private renters who are currently receiving Housing Benefit or the housing element of Universal Credit. Specifically, those whose current benefit amount is capped by the LHA rate for their area and household size are most likely to see a positive impact. If the 2.9% increase raises the LHA rate above their current eligible rent, they may receive more financial assistance towards their housing costs.
It’s also important to note that the adjustment can be particularly helpful for new claimants or those moving to a new property, as the updated LHA rates will apply to their initial assessment. This could potentially open up a wider range of affordable rental options for them compared to what was available under previous, lower LHA caps. The aim is to ensure that the benefit system can better support individuals and families in securing suitable accommodation.
However, it’s crucial to remember that not everyone will experience a direct increase in their payments. If your eligible rent is already below the updated LHA rate, or if other income or savings factors limit your overall Housing Benefit entitlement, the LHA rate adjustment might not translate into a higher payment for you. The benefit system takes a holistic view of a claimant’s financial situation, and the LHA rate is just one piece of that complex puzzle, albeit a significant one for many.
Understanding Your Local Housing Allowance
Understanding your specific Local Housing Allowance (LHA) is fundamental to grasping how the recent adjustments might affect you. LHA rates are not uniform across the UK; they are determined by ‘Broad Rental Market Areas’ (BRMAs), which are geographical areas where people would reasonably look for private rented accommodation. This means that someone living in central London will have a vastly different LHA rate compared to someone in a rural village, reflecting the differing market rents in those locations.
To find your LHA rate, you generally need to know your postcode and the number of bedrooms you are entitled to. The number of bedrooms is determined by specific rules, usually one bedroom for each of the following: a single adult or couple, other adults aged 16 or over, and two children of the same gender under 16, or two children of any gender under 10. There are also specific rules for disabled individuals requiring overnight care.
Once you know your BRMA and bedroom entitlement, you can use official government websites to look up the precise LHA rate applicable to you. This rate represents the maximum housing benefit you can receive, regardless of your actual rent. If your rent is higher than the LHA rate, you will need to cover the difference yourself. If your rent is lower, your benefit will typically be capped at the actual rent amount, assuming no other deductions apply.
Key Factors Affecting Your LHA Rate:
Location: Different Broad Rental Market Areas (BRMAs) have varying rates.
Household Size: The number of bedrooms you are entitled to based on who lives with you.
Type of Accommodation: LHA rates are typically for self-contained accommodation.
Date of Claim: Rates can change over time, so the rate applicable at the start of your claim is important.
Regularly checking the LHA rates for your area is a good practice, especially following announcements of adjustments like the recent 2.9% increase. This ensures you have the most up-to-date information regarding your potential housing support.
Impact on Renters: Bridging the Gap?
The 2.9% LHA rate adjustment is a step towards addressing the ongoing challenge many renters face in affording suitable housing, but its effectiveness in truly bridging the gap between housing benefit and actual market rents is a complex issue. For years, LHA rates have often lagged behind the rapid increase in private rental costs, leading to significant shortfalls that claimants have had to cover themselves. This gap has placed considerable financial strain on low-income households, sometimes forcing them into difficult choices or unsuitable accommodation.
While a 2.9% increase offers some relief, it’s crucial to consider whether this percentage keeps pace with current rental inflation in specific areas. In many parts of the UK, rents have risen by significantly more than 2.9% over the past year, meaning that even with the adjustment, the LHA rate might still fall short of covering average market rents. This leaves many renters still facing a deficit, albeit potentially a slightly smaller one than before the adjustment.
The impact will also vary depending on the specific LHA rate. For areas with historically lower LHA rates, a 2.9% increase might feel less impactful than in areas where the rates were already higher. Ultimately, while the adjustment is a positive move, it highlights the need for ongoing monitoring and potentially more substantial interventions to ensure that housing support adequately reflects the realities of the private rental market across the country. Renters need to remain vigilant about their local market conditions.
Navigating Changes and Seeking Support
Navigating the complexities of Housing Benefit and the recent LHA rate adjustment can feel daunting, but there are clear steps renters can take to ensure they are well-informed and receiving the support they are entitled to. The first crucial step is to verify how the 2.9% adjustment impacts your specific LHA rate. This can typically be done via the government’s official LHA rate checker, where you input your postcode and bedroom entitlement to see the updated figures for your Broad Rental Market Area.
Once you understand your new maximum entitlement, compare it against your actual rent. If there’s a shortfall, it’s important to budget for this difference or explore options for reducing your housing costs. If you are already receiving Housing Benefit or Universal Credit, you don’t usually need to take immediate action; the Department for Work and Pensions (DWP) or your local council should automatically update your claim based on the new rates. However, it’s always wise to check your benefit statements to confirm the changes have been applied correctly.
If you find yourself struggling to cover your rent even with the adjusted LHA rate, don’t hesitate to seek further support. There are numerous organisations dedicated to assisting renters with their housing and financial challenges. These services can offer personalised advice, help you understand additional benefits you might be eligible for, or even assist in negotiating with your landlord. Being proactive and seeking guidance early can make a significant difference in managing your housing situation effectively.
Frequently Asked Questions
Will my Housing Benefit automatically increase with the 2.9% LHA rate adjustment?
Your Housing Benefit or Universal Credit housing element may increase if your current payment was capped by the previous LHA rate and the new rate is higher. The DWP or your local council should apply these changes automatically, but it’s always good practice to check your updated benefit statements.
How can I find out my specific LHA rate after the adjustment?
You can find your specific LHA rate by using the official government website’s LHA rate checker. You will need to enter your postcode and indicate the number of bedrooms you are entitled to based on your household composition.
What if my rent is still higher than the adjusted LHA rate?
If your rent remains higher than the adjusted LHA rate, you will be responsible for covering the difference yourself. In such cases, it’s advisable to seek advice from housing charities or your local council, as you might be eligible for Discretionary Housing Payments (DHPs) or other forms of assistance.
Does the LHA rate adjustment apply to all renters receiving housing support?
The LHA rate adjustment applies to private renters receiving Housing Benefit or the housing element of Universal Credit. It does not directly affect social housing tenants, whose rent is typically covered by different benefit calculations.
Where can I get help if I’m struggling with my rent after the LHA adjustment?
If you’re struggling, contact your local council’s housing department, or seek advice from independent housing charities like Shelter or Citizens Advice. They can offer tailored guidance, help you explore all available options, and ensure you’re accessing all eligible support.
The 2.9% LHA rate adjustment represents a crucial, albeit often nuanced, development for private renters relying on Housing Benefit or Universal Credit. While it offers a welcome increase in the maximum amount of support available, its real-world impact will vary significantly depending on individual circumstances and local market conditions. Understanding how this adjustment affects your specific entitlement is the first step towards managing your housing costs effectively.
We’ve explored who stands to benefit most, how to ascertain your local LHA rate, and the broader context of bridging the gap between benefit levels and market rents. Remember that proactive engagement with official resources and seeking expert advice from housing organisations can provide vital support. Staying informed and taking appropriate action will empower you to navigate these Housing Benefit updates and secure your housing stability in an ever-evolving rental landscape.
By understanding these changes, renters can better plan their finances and advocate for their needs, ensuring they receive the full extent of the support they are entitled to. This adjustment, while not a panacea, is an important part of the ongoing conversation around affordable housing in the UK.
pedropadm2025@gmail.com
Peter B holds a degree in Journalism and has 5 years of experience covering U.S. economic policy, labor markets, and financial news. He writes data-driven news content on topics like inflation, interest rates, and employment trends.