Benefit Cap Explained: Understanding the £23,000 Limit
This article offers a comprehensive overview of the Benefit Cap, explaining its purpose, how it affects households, and the £23,000 limit. Discover strategies to navigate its impact and find crucial support resources.
By: pedropadm2025@gmail.com on August 22, 2026
Última atualização em: agosto 24, 2026
Benefit Cap Explained: Understanding the £23,000 Limit
The Benefit Cap is a significant aspect of the UK’s welfare system, designed to limit the total amount of welfare benefits a household can receive. For many families, understanding the Benefit Cap explained can be crucial for managing their finances and planning for the future. This policy sets a maximum amount on the total benefits that most working-age people can get, impacting thousands of households across the country, particularly those with multiple children or living in high-rent areas.
Initially introduced in 2013 and subsequently revised, the cap aims to encourage people into employment and ensure fairness in the benefits system. The current limit is £23,000 per year for couples and single parents in Greater London, and £20,000 per year for those outside of London, with different, lower rates for single adults without children. Grasping the nuances of this cap is essential for anyone who might be affected, allowing them to anticipate potential reductions and explore available support.
What is the Benefit Cap and How Does It Work?
The Benefit Cap is a limit on the total amount of certain welfare benefits that most people aged 16 to 64 can receive. This cap applies to the combined amount of various benefits, not just one specific payment. The government introduced this measure to ensure that households on out-of-work benefits do not receive more than the average earnings of working households. It’s a complex system, and many people find themselves caught off guard by its application, leading to unexpected shortfalls in their household income.
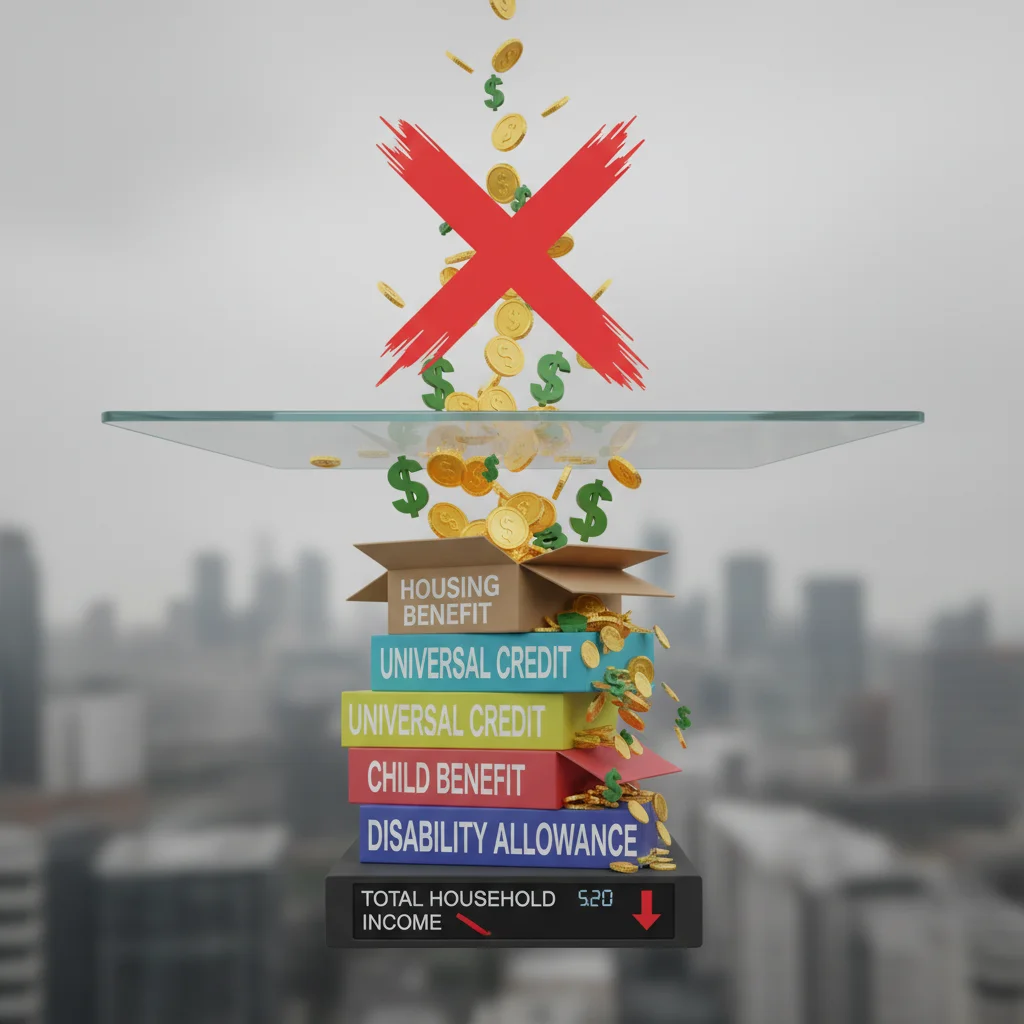
When your total benefits exceed the cap, your Universal Credit payments are usually reduced to bring your overall benefit income down to the capped level. If you are not claiming Universal Credit, your Housing Benefit is typically reduced instead. This reduction can have a profound effect on a household’s ability to cover essential living costs, especially rent, which often makes up a large portion of a family’s expenditure. Therefore, understanding which benefits count towards the cap and which are exempt is a vital first step for anyone concerned about their financial situation.
The cap is applied differently depending on your household circumstances and where you live. For example, the annual cap for a single parent or couple in Greater London is £23,000, which translates to approximately £442.31 per week. Outside of Greater London, this figure drops to £20,000 per year, or about £384.62 per week. For single adults without children, the cap is even lower, set at £15,410 per year (£296.35 per week) in Greater London and £13,400 per year (£257.69 per week) outside London. These varying thresholds highlight the importance of knowing your specific situation when calculating the potential impact.
Which Benefits Are Included and Excluded from the Cap?
Understanding which benefits contribute to the cap and which are exempt is crucial for calculating your potential exposure. The cap applies to a range of common benefits that many households rely on. Knowing these specifics can help you assess your current financial situation accurately and anticipate any potential reductions. It’s not just a single benefit that gets capped; rather, it’s the cumulative total of several different payments.
Benefits that are included when calculating the Benefit Cap typically encompass Universal Credit (unless you’re exempt), Housing Benefit, Jobseeker’s Allowance, Income Support, Employment and Support Allowance (unless you’re in the support group), Child Benefit, and Child Tax Credit. Additionally, other benefits like Guardian’s Allowance, Carer’s Allowance, and Bereavement Allowance also fall under the cap. This broad inclusion means that many families could find their total benefit income exceeding the set limits, even if they don’t receive particularly high amounts from any single benefit.
Benefits That Count Towards the Cap:
Universal Credit (with exceptions)
Housing Benefit
Child Benefit and Child Tax Credit
Jobseeker’s Allowance (income-based)
Income Support
On the other hand, several benefits are entirely exempt from the cap, meaning they are not included in the calculation of your total benefit income. These exemptions are vital for ensuring that support for certain vulnerabilities or circumstances remains protected. Benefits that are exempt from the cap include Personal Independence Payment (PIP), Disability Living Allowance (DLA), Attendance Allowance, and the support component of Employment and Support Allowance (ESA). Also exempt are Industrial Injuries Disablement Benefit, War Disablement Pension, Armed Forces Compensation Scheme payments, and the limited capability for work related activity element of Universal Credit. If you or someone in your household receives any of these exempt benefits, the cap will not apply to your household, providing a crucial safety net for those with specific needs. This distinction often determines whether a household is affected by the cap at all.
Who is Exempt from the Benefit Cap?
While the Benefit Cap affects a significant number of households, there are specific circumstances and benefits that can lead to an exemption, meaning the cap will not apply to you. Understanding these exemptions is paramount for anyone who might be at risk of having their benefits reduced. These exemptions are designed to protect the most vulnerable individuals and families, ensuring they receive the full support they need without arbitrary limitations. It’s important to check if any of these apply to your household, as an exemption can make a substantial difference to your income.
One of the primary exemptions relates to employment. If you or your partner are working and your earnings are above a certain threshold, you will typically be exempt from the cap. This threshold is currently set at £722 per month after tax and National Insurance for Universal Credit claimants. For those receiving Housing Benefit, the threshold is slightly different, usually based on working 16 hours a week at the National Living Wage. This exemption aims to support those who are actively engaging with the job market, reinforcing the policy’s objective of encouraging employment. Therefore, even part-time work can be a pathway to avoiding the cap.
Furthermore, households receiving certain disability benefits are also exempt. If you, your partner, or any child living with you receives Disability Living Allowance (DLA), Personal Independence Payment (PIP), Attendance Allowance, or the support component of Employment and Support Allowance (ESA), the cap will not apply. This also includes those receiving Industrial Injuries Disablement Benefit, War Disablement Pension, or payments from the Armed Forces Compensation Scheme. These exemptions acknowledge the additional costs and challenges faced by individuals with disabilities, ensuring their essential support is not compromised. It’s vital to ensure all eligible disability benefits are claimed to secure this protection.
There are also temporary exemptions that can apply. For instance, if you were working for 12 months or more and then lost your job or had your hours reduced, you might be exempt from the cap for a grace period of nine months. This ‘grace period’ allows individuals and families time to adjust to their new circumstances and potentially find new employment without immediate benefit reductions. Additionally, if you are a carer and receive Carer’s Allowance, or if you are receiving Guardian’s Allowance, you are also exempt from the cap. These provisions demonstrate an effort to balance the policy’s aims with the need to protect those in specific, vulnerable situations.
Strategies to Mitigate the Impact of the Benefit Cap
If you find that your household is affected by the Benefit Cap, it’s natural to feel worried about your financial stability. However, there are several strategies and avenues of support available that can help mitigate its impact. Taking proactive steps and seeking advice can make a significant difference in managing your household budget and ensuring you access all the assistance you are entitled to. The key is to act early and explore all possible options to reduce the financial strain caused by the cap.
One of the most effective ways to avoid or reduce the impact of the Benefit Cap is to increase your earnings. Even working a few hours a week can make a difference, as reaching the earnings threshold for Universal Credit (£722 per month after tax and National Insurance) will exempt you from the cap entirely. If you are able to work, exploring part-time employment, increasing your hours, or seeking better-paid work should be a priority. Government initiatives and local employment support services can often provide assistance with job searching, CV writing, and interview skills, making this path more accessible.
Another crucial strategy is to ensure you are claiming all the benefits you are entitled to, particularly those that are exempt from the cap. For instance, if you or a family member has a disability or long-term health condition, check eligibility for benefits like Personal Independence Payment (PIP) or Disability Living Allowance (DLA). Receiving one of these exempt benefits will lift the cap for your entire household. It’s common for people not to realise they are eligible for these benefits, so a thorough benefit check with an advisor can be incredibly valuable. Even if you’ve been turned down before, circumstances change, and it might be worth reapplying or seeking advice on appeals.
Key Mitigation Strategies:
Increase household income through employment.
Claim all eligible disability benefits (e.g., PIP, DLA).
Seek Discretionary Housing Payments (DHPs).
Explore options for moving to cheaper accommodation.
Get free, impartial financial advice.
Additionally, if your Housing Benefit or Universal Credit housing element is reduced due to the cap, you may be eligible for a Discretionary Housing Payment (DHP) from your local council. DHPs are short-term payments that can help cover housing costs when there is a shortfall. While they are not a long-term solution, they can provide vital temporary relief and allow you time to implement more sustainable strategies. It’s essential to apply for DHPs as soon as you know you will be affected by the cap, as funds are limited and allocated at the council’s discretion. Seeking advice from a local welfare rights organisation or Citizens Advice can help you navigate the application process and understand your full range of options.
Seeking Support and Advice for the Benefit Cap
Navigating the complexities of the Benefit Cap can be daunting, and attempting to understand all the rules and potential impacts on your own can be overwhelming. Fortunately, there are numerous organisations and resources dedicated to providing free, impartial advice and support to individuals and families affected by welfare reforms. Reaching out to these services can provide clarity, help you understand your rights, and guide you through the process of mitigating the cap’s effects. You don’t have to face this challenge alone; expert help is readily available to assist you.
One of the most widely recognised sources of support is Citizens Advice. They offer comprehensive advice on benefits, housing, debt, and employment, and can help you understand how the Benefit Cap applies to your specific situation. Their advisors can assist with benefit checks, help you apply for Discretionary Housing Payments, and even support you in challenging benefit decisions. Many local councils also have welfare rights teams or housing advisors who can offer specialised guidance on the Benefit Cap and its implications for your housing costs. These local services often have a deep understanding of regional housing markets and specific council policies, which can be invaluable.
For more specific issues, such as those related to disability benefits, organisations like Scope, Mencap, or Disability Rights UK can provide tailored advice and support. If you are struggling with debt as a result of the cap, charities like StepChange Debt Charity or National Debtline offer free debt advice and solutions. These organisations can help you create a budget, negotiate with creditors, and explore options for managing your financial commitments. It is crucial to address debt issues promptly, as they can quickly escalate and create further stress.
Additionally, many housing associations and local charities offer support services for their tenants and local residents. They might provide budgeting advice, help with employment searches, or connect you with other local support networks. Don’t hesitate to check what services are available in your immediate community. Engaging with these support systems not only provides practical assistance but also offers emotional reassurance during a challenging time. Remember, the goal is to empower you with the information and tools needed to navigate the Benefit Cap effectively and maintain your household’s financial stability.
Frequently Asked Questions
Q: How quickly will the Benefit Cap affect my payments once applied?
A: Once the Benefit Cap is applied, your benefits will be reduced from the next payment cycle. It’s crucial to be aware of the exact date to plan your finances accordingly.
Q: Can I appeal a Benefit Cap decision?
A: Yes, you can appeal a Benefit Cap decision if you believe it has been applied incorrectly or if you are exempt. You should first request a mandatory reconsideration, and if still unsatisfied, you can appeal to an independent tribunal.
Q: Does the Benefit Cap apply to everyone receiving benefits?
A: No, the Benefit Cap does not apply to everyone. There are significant exemptions for individuals and households receiving certain disability benefits or earning above a specific threshold from employment.
Q: What if my circumstances change after the cap is applied?
A: If your circumstances change, for example, you start working, your earnings increase, or someone in your household becomes eligible for an exempt benefit, you must inform the Department for Work and Pensions (DWP) or your local council immediately. This could lead to the cap being lifted.
Q: Where can I find a Benefit Cap calculator to estimate its impact?
A: The UK government website provides a Benefit Cap calculator where you can input your details to estimate how much your benefits might be affected. Many advice organisations also offer similar tools or direct assistance with calculations.
Understanding the Benefit Cap explained is more than just knowing a figure; it’s about grasping its potential impact on your household and proactively seeking solutions. The £23,000 limit, or £20,000 outside London, significantly shapes the financial landscape for many families in the UK. We’ve explored how the cap works, which benefits are included and excluded, and the vital exemptions that can protect vulnerable households. Crucially, we’ve outlined practical strategies, from increasing your earnings to claiming all eligible benefits and applying for Discretionary Housing Payments, to help mitigate its effects.
The journey through welfare reforms can be complex, but with the right information and support, you can navigate these challenges effectively. Remember that organisations like Citizens Advice and local welfare rights teams are invaluable resources, offering free, impartial guidance tailored to your specific circumstances. Taking the initiative to seek advice and explore all available options is the most powerful step you can take. By empowering yourself with knowledge and leveraging the support networks available, you can work towards maintaining your financial stability and securing a more stable future for your household, even under the constraints of the Benefit Cap.
pedropadm2025@gmail.com
Peter B holds a degree in Journalism and has 5 years of experience covering U.S. economic policy, labor markets, and financial news. He writes data-driven news content on topics like inflation, interest rates, and employment trends.